

CPA for Startups
A CPA Who Understands What Startups Actually Need
A CPA for startups - or an accountant for startups, whichever term you use — has to move at founder speed, understand why a pre-revenue company still has real financial decisions to make, and know when a bookkeeping subscription stops being enough.
Tell us about your Accounting needs.
Schedule a 15-minute call with a CPA.
What Startups Need From an Accountant (and When)
Pre-Revenue vs. Post-Funding - Different Needs
The Pre-Revenue Stage
When a startup is pre-revenue, management often assumes accounting can wait. However, decisions made before generating a dollar of income dictate future tax obligations and investor readiness.
Expense Tracking & Capital Contributions: From day one, things like founder contributions, personal software subscriptions, and initial equipment purchases need to be classified correctly. Get this wrong early, and it's capital that won't be accounted for properly down the line.
Tax Compliance: Even a business with no revenue yet still has to file annual federal and state tax returns. Skipping this isn't just a paperwork issue, it puts legal standing at risk.
Elections & Intellectual Property: Some filings can't slip. Take the 83(b) election with the IRS, for instance, it has to be filed within 30 days of receiving equity subject to vesting, or you're looking at unexpected personal income tax liabilities later that could've been avoided entirely.
How It Works
The Post-Funding & Scaling Stage
Simple Agreements for Future Equity
Everything changes once a startup raises seed capital, issues Simple Agreements for Future Equity (SAFEs), or starts generating recurring revenue. Financial requirements don't shift gradually here, they shift fast.
Burn Rate & Runway Management
Investors want accurate numbers. Burn rate tells you how quickly cash reserves are shrinking. Runway tells you how many months of operations are left before more capital becomes necessary.
Cap-Table-Adjacent Bookkeeping
SAFEs, convertible notes, option pools, all of it needs to show up accurately on the balance sheet, but without cluttering the operational numbers that actually run the business day to day.
Investor Transparency
Angel investors and venture firms aren't going to take your word for it. They'll want clear financial reports, Balance Sheet, Income Statement, Cash Flow Statement, to track performance and verify that governance is actually in order.
What you get
Get the Entity Structure Right From Day One
Determining the best entity structure for a startup comes down to the following factors
LLC
It is flexible and simple, often a reasonable starting point pre-fundraise.
S-corp
It can reduce self-employment tax exposure for profitable, owner-operated businesses.
Delaware C-corp
It is the default choice for startups planning to raise venture capital.
Timing matters
Per IRS instructions for Form 2553, an election for S-corp status has to be filed no later than two months and 15 days after the date the election is meant to take effect, miss that window, and the timing works against you. Separately, qualified small businesses with R&D activity may be eligible to apply up to $500,000 of the federal R&D tax credit against payroll tax liability per year, under current IRS guidance.
Reference: SBA — Choosing a Business Structure · IRS — Instructions for Form 2553

Burn Rate and Runway
Why Startups Need to Track Both
There are two most important and critical figures that every start‐up should be evaluating in the first years of its development. These are the burn rate and the runway. The former stands for the amount of money that a company spends on a monthly basis, while the latter is the number of months that the business can operate with the current level of expenditure.
Together, they answer the question every founder eventually has to face: how long do we have before we need more revenue, more funding, or a change in spending?
Tracking these numbers isn't just useful internally. Investors ask about burn rate and runway during due diligence because it shows whether a founder understands their own financial position. A founder who can't answer clearly, or whose numbers don't match their actual bank balance, raises questions before a term sheet is even on the table.
This is where bookkeeping and accounting intersect directly. Accurate, up-to-date books make burn rate and runway easy to calculate at any given moment. Without that foundation, founders are often estimating, and estimates tend to be wrong in the direction that matters least, overestimating the runway they actually have left. This is exactly the kind of gap a CPA for startups is built to close, turning raw numbers into a clear, current read on where the business stands.
Accounting For StartUp
Accounting Built for Where Your Startup Actually Is
At the very early stages, most startups do not require a full-blown advisory role; they require clear books, an understanding of their burn rate, and a person who can help to spot a tax or entity choice that could be costly to reverse later. As the company progresses, those needs evolve into tax planning, payroll establishment, and financial reporting that will hold up under scrutiny.
Entity structure guidance before you incorporate, not after
Startup bookkeeping that gives founders a real-time read on cash position
Tax planning that accounts for burn rate, runway, and upcoming funding or hiring
Payroll setup once the company brings on its first employees
The Problem
What’s Included in Our CPA for Startups Accounting Services
Our startup CPA firm provides hands-on financial management tailored to early-stage requirements. We replace fragmented software tools and reactive tax filers with an integrated accounting foundation.
1
Startup Bookkeeping & Chart of Accounts Setup
Generic bookkeeping often lists software subscriptions, cloud hosting, and contractor payments under vague expense categories. We build a clean chart of accounts tailored to your operational model.
2
Burn Rate & Runway Analysis
Knowing your precise cash burn is vital for maintaining a runway. We provide founders with clear monthly reconciliations showing your net burn (cash receipts minus cash disbursements) and gross burn (total monthly operating expenses). This insight allows you to make informed hiring, marketing, and expansion decisions well before cash reserves run low.
3
Cap-Table-Adjacent Ledger Management
When early investors back your company using SAFE notes or convertible debt, tracking capital entries on your balance sheet is critical. We ensure these funding instruments are correctly recorded, preserving financial clarity for future priced rounds.
4
Multi-State Payroll & Tax Nexus Support
As remote hiring becomes the norm, startups frequently hire developers, sales representatives, and executives across state lines. Hiring an employee in another state creates payroll tax nexus and potentially income or sales tax filing obligations in that jurisdiction. We establish compliance frameworks so remote team expansion does not cause audit exposure.
WHO WE SERVE
Built for Founders at Every Stage
Pre-Revenue Startups
Setting up financial systems from day one, before revenue or funding complicates things.
Post-Funding Companies
Need organized reporting and payroll set up correctly after a raise.
Remote & Multi-State Teams
Founders and teams spread across states, supported through our virtual CPA firm model.
The Solution
We Work With Startups Anywhere
While Arthur S. Lazarus, CPA, a trusted CPA for Startups, is rooted in South Florida-serving entrepreneurs in Fort Lauderdale - Hollywood and Broward County-we serve founders across the United States.
Modern early-stage companies operate in digital-first environments. Our cloud-based accounting infrastructure allows founders to collaborate with a licensed CPA seamlessly, regardless of physical location. Through secure document portals, cloud accounting software integrations, and structured video consultations, you gain access to high-level CPA advisory without geographic limits.
To learn more about working with us remotely, visit our Virtual CPA Firm Services page.
Experience You Can Verify
Who Reviews Your Startup's Books
Your financial data never leaves our firm. A licensed CPA leads each engagement, remote or in-person.
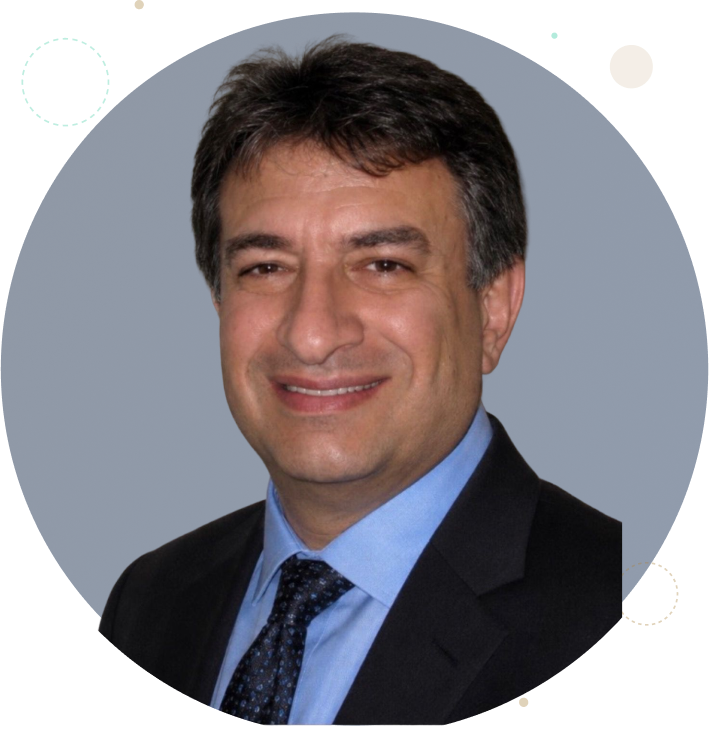
Arthur S. Lazarus, CPA
Founder & Managing Partner — Licensed in Florida (AC61458) and Maryland (13054)
Arthur Lazarus is a CPA licensed in Florida and Maryland, with a Master's in Taxation, and a member of the FICPA, the Fort Lauderdale Chamber of Commerce, and the Hollywood Chamber of Commerce. Financial challenges, objectives, and opportunities vary from one startup to another, which is why entity and tax decisions are handled based on your specific plans, not a set formula.
Files move through a secure portal. We never ask for financial records over plain email.
Licensed Oversight
A licensed CPA reviews every engagement, from entity setup through ongoing bookkeeping and tax planning, regardless of delivery method.
Find out more about Arthur: https://www.linkedin.com/in/arthurlazaruscpa/
The Problem
Why Startup Accounting Falls Behind
Founders are busy building the product and closing the round. Accounting is usually the thing that gets pushed off, until it can't be anymore.
1
The Entity Decision Gets Made Too Fast
LLC, S-corp, or Delaware C-corp - many founders pick whichever their incorporation service defaults to, without weighing what it means for taxes or fundraising later.
2
Spreadsheet Bookkeeping Doesn't Scale
What works pre-revenue usually breaks down after the first few hires or the first fundraise, right when investors start asking for real financial statements.
3
Tax Decisions Get Made in April
By the time most founders think about tax planning, the year's decisions are already locked in and the savings are gone.
What You Get
When Should a Startup Hire a CPA?
Most founders wait way longer than they should. Ideally, you bring a CPA for startups in right when you incorporate, before that first tax deadline catches you off guard. Why so early? Because entity mistakes, bookkeeping gaps, and payroll setup issues are cheap to fix now and expensive to untangle later.
A few considerations make it stop being optional, though:
You've just incorporated or formed an LLC
Tax elections like S-corp status come with strict deadlines, easy to miss if nobody's watching for them.
Outside capital is coming in.
Investors expect clean books. A CPA who's worked with startups before knows how to prepare financials that actually survive due diligence.
You hired someone.
Once payroll enters the picture, so does withholding, quarterly filings, and compliance risk, and mistakes here aren't cheap.
Revenue's climbing month over month.
A spreadsheet stops cutting it fast. That's usually the point real bookkeeping and reporting become necessary, not optional.
You're seeking a loan or credit line.
Lenders want CPA-reviewed statements. DIY numbers generally won't cut it.
What's the Difference ?
Startup Accounting vs. Bookkeeping
Startup owners think bookkeeping and accounting are one and the same, but in reality, these two processes serve different purposes in establishing the foundation for financial success. The former refers to the ongoing task of recording all transactions, making sure that no data goes unrecorded and no mistake is left unaddressed.
Startup accounting utilizes bookkeeping information in order to make important business decisions based on the collected financial data, for example, cash flow projections, tax management, and financial reports needed by the investors. At Arthur S. Lazarus, CPA, we combine our Bookkeeping and Small Business Accounting services to provide startups with a clear financial record and strategic direction.
CPA FOR STARTUPS
Frequently Asked Questions
Does a pre-revenue startup need an accountant?
Yes. Even before there's revenue, startups still have federal and state filing obligations, and startup costs may be deductible under Section 195 if tracked from day one. Founder contributions and early expenses also need to be recorded properly so your financial picture is accurate once revenue starts coming in.
How does a startup know if they need a bookkeeper or a CPA?
The bookkeeper is responsible for the basic tasks of transaction recording, expense categorization, and account reconciliation. The CPA, however, goes beyond that to provide advice on business formation, understanding IRS regulations, R&D credit, multi-state tax issues for remote employees, and producing reliable financial reports.
Can you help us choose between an LLC, S-corp, and Delaware C-corp?
Yes. We look at your fundraising plans, ownership structure, and tax situation, and work alongside your legal counsel so the entity choice lines up with your cap table and any funding agreements.
At what point should a startup actually hire a CPA?
Ideally right when you incorporate, before your first tax deadline or S-corp election window closes. It becomes non-negotiable once outside capital, payroll, or a loan application enters the picture - investors and lenders expect CPA-reviewed numbers, not a spreadsheet.
Do you work with startups outside Florida?
Yes. We work with founders in Fort Lauderdale, Hollywood, and Broward County directly, and support startups elsewhere in the country through our virtual CPA model.
Get Started Today
Build Your Startup on a Solid Financial Foundation
Book a free 30-minute call with a licensed startup CPA. We'll look at where you are, whether that's pre-revenue, prepping for a raise, or scaling post-funding, and show you what to prioritize first. No cost. No pressure.
Contact Us
Get in Touch
Office Info
Phone
Address
5184 SOUTHWEST 32ND AVENUE
FORT LAUDERDALE, FLORIDA 33312
Hours
Mon–Fri 8am – 6pm
Sat 9am – 2pm
Follow us

